
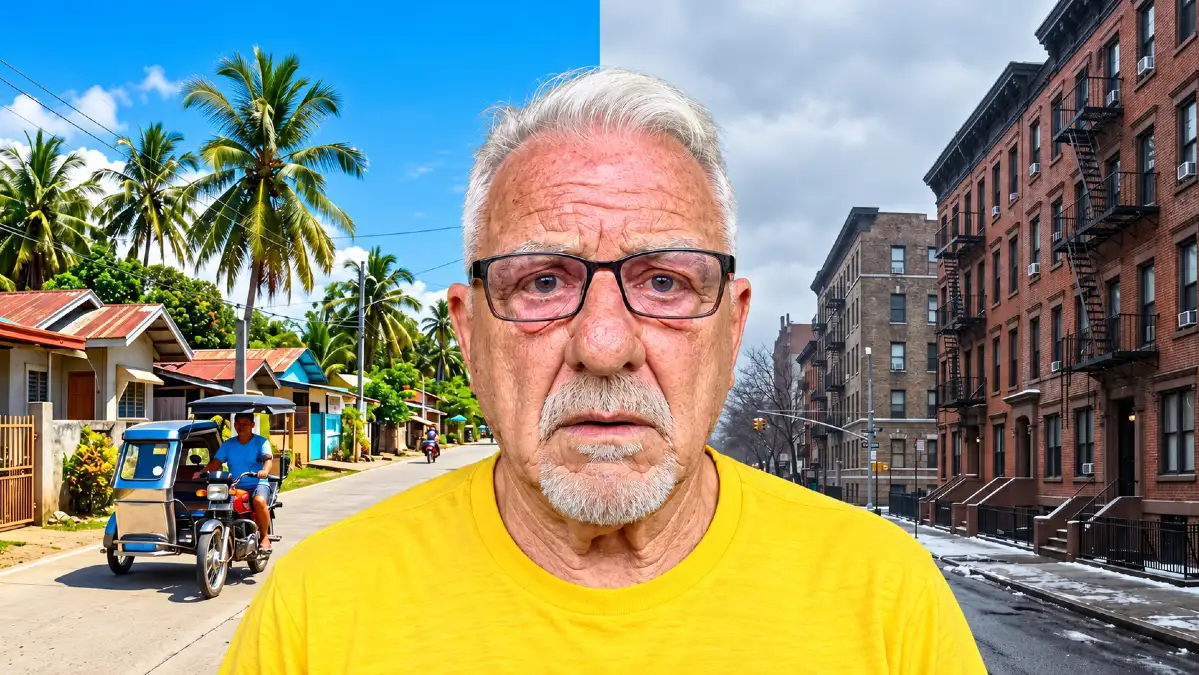
Retiring abroad sounds like the perfect escape from rising costs, expensive housing, and financial pressure. A smaller retirement check can stretch further, everyday life may feel more relaxed, and the thought of starting fresh somewhere beautiful can be hard to resist.
But what happens when that new country becomes your permanent home, and returning to America no longer makes financial sense?
What happens when the friends you left behind have moved on, your old home is gone, and the country where you now live still considers you a foreigner?
After nine years living in the Philippines, 71-year-old American retiree Paul has reached a difficult realization. He loves his life overseas, but returning to the United States would mean rebuilding almost everything from the beginning.
The Move That Was Supposed to Be Temporary Became Permanent
When Paul first traveled to the Philippines, he wasn’t planning a permanent move. He wanted to experience the country, see whether he enjoyed living there, and decide what to do next.
He wasn’t thinking about immigration, long-term retirement planning, or whether he would ever return to America. At the time, everything felt temporary, and going home remained an option.
Then one year passed. Before he fully realized what was happening, that first year had become three, and eventually, he had spent nearly a decade living overseas.
During those years, his life in America slowly disappeared. The condo he once had was gone, his car was gone, and the routines that had connected him to his old life faded away.
Nothing happened overnight. Instead, dozens of small decisions gradually turned a temporary adventure into a permanent way of life.
That is one of the first surprises of retiring abroad. You can become a long-term resident without ever making one clear decision to stay forever.
For retirees considering an overseas move, this matters more than it first appears. Renting out a home, selling possessions, closing accounts, and allowing relationships to fade can make returning increasingly difficult.
A temporary move may feel completely reversible during the first few months. After several years, however, rebuilding the life you left can become a much bigger project than moving overseas in the first place.
Your Retirement Income May Work Overseas but Fail Back Home
One of the main reasons Paul remains in the Philippines is financial.
He receives approximately $2,233 per month in Social Security after his Medicare Part B deduction, according to his account. He also earns additional income from his YouTube channel.
Together, those income sources allow him to maintain a comfortable everyday lifestyle in the Philippines.
He can pay his rent, buy groceries, cover utilities, purchase fuel, and enjoy occasional evenings out. He can also help provide for his wife, May, while putting a little money aside when the month goes well.
This doesn’t mean he lives an extravagant lifestyle. It means his income supports the kind of ordinary, comfortable retirement he wants.
The situation changes when he considers moving back to the United States.
Paul estimates that renting a modest apartment in an American city could cost around $1,500 per month. That is his planning example, not a reliable national average for every city.
Here is what that hypothetical rent would mean for his Social Security income.
| Monthly Expense or Income | Amount |
|---|---|
| Social Security after Part B deduction | $2,233 |
| Estimated U.S. apartment rent | -$1,500 |
| Money remaining after rent | $733 |
| Groceries, transportation, utilities, insurance | Not yet deducted |
| Emergency savings | Not yet funded |
That remaining $733 would need to cover electricity, food, transportation, insurance, household supplies, and unexpected expenses.
And Paul would still need to figure out how to buy or maintain a car.
The same retirement income that provides a comfortable lifestyle in one country could leave him financially strained in another.
This is the hidden risk of geographic retirement savings. Your money may go further in a cheaper country, but that doesn’t mean you have enough financial resources to maintain the same lifestyle elsewhere.
Lower living costs can improve retirement. They can also create a situation where staying abroad becomes the only financially attractive option.
Returning Home Can Mean Starting Over at 70
Paul’s challenge isn’t simply that American housing might be expensive. It is that he would have to rebuild the basic parts of his life.
He no longer owns his former condo or car. Returning would mean finding housing, arranging transportation, buying everyday necessities, and establishing a new routine.
At 71, those tasks feel very different from starting over at 25.
He also worries about employment. After spending almost ten years overseas, he doubts that employers would be eager to hire someone his age with such a long break from the American workforce.
That doesn’t mean older adults cannot find employment. Many do, particularly through part-time work, consulting, or jobs that value experience.
But depending on finding a job immediately after returning would introduce real financial uncertainty.
Another concern is his credit history. Paul has kept one American credit card active, but he isn’t sure whether that would be enough to qualify for an apartment.
Living overseas does not automatically erase someone’s credit score. Still, limited recent credit activity and missing rental references can complicate a move back.
For someone returning after many years, even everyday tasks may require planning.
| What Paul Left Behind | What Returning Could Require |
|---|---|
| His former condo | Finding and qualifying for housing |
| His old vehicle | Buying a car and obtaining insurance |
| Familiar employment connections | Rebuilding a professional network |
| Established social relationships | Reconnecting or making new friends |
| His former daily routine | Creating a new life from the beginning |
Paul is not saying that returning would be legally impossible. As an American citizen, he can return to the United States.
His concern is that the financial and personal cost of returning could leave him with a much harder life than the one he currently enjoys.
For many retirees, that distinction matters. Having the right to return and having the resources to rebuild are two different things.
The Income You Depend On Might Not Follow You Home
Paul has another financial concern that many retirees overlook.
His Social Security income would generally continue if he returned to America. But the additional money he earns through his YouTube channel is less predictable.
His videos focus on his experiences living in the Philippines. He worries that viewers might lose interest if he stopped living overseas and started making videos about ordinary life back in America.
That income could decline, although it isn’t certain that it would disappear.
This reveals an important financial risk for retirees who earn extra money abroad. Some income sources depend on where you live, what you do, or the lifestyle that attracts your customers and audience.
A retired American teaching English overseas might lose that income upon returning home. Someone managing a small tourism business might face the same problem.
Even part-time freelance work can change when costs, schedules, or personal circumstances change.
The lesson is to separate dependable retirement income from money that might disappear after a major move.
Social Security can often continue while living overseas, subject to eligibility and country-specific payment rules. The Social Security Administration advises beneficiaries to check those rules before relocating.
For Paul, the uncertainty surrounding his additional income makes a return to America feel even less financially realistic.
The Cheapest Way to Return Might Not Be the Life You Want
Paul recognizes that there might be cheaper ways to live in America.
He could potentially rent a room instead of an apartment. He might buy an inexpensive used car, purchase basic insurance, and reduce his spending to the minimum.
He even jokes that these are the kinds of things he did when he was 19.
But doing something because it is possible and doing it because it creates a satisfying retirement are not the same.
After decades of working and raising a family, many older adults want a degree of stability. They want a comfortable place to live, reliable transportation, and enough financial freedom to enjoy their remaining years.
Paul already has those things in the Philippines.
Returning to America only to live in a rented room, constantly watching expenses, could feel like giving up much of the life he has built.
This raises a question that every retiree thinking about returning home should consider.
Are you returning because life will be better, or simply because you feel you are supposed to go back?
There is nothing wrong with living simply. For some people, sharing housing or owning an older car is a perfectly satisfying choice.
The concern appears when those arrangements are the only affordable options, and they offer less comfort, independence, or stability than the life already available overseas.
The Friends You Left Behind May No Longer Be There
Money is only one part of Paul’s story.
When he thinks about returning to America, he also wonders who would be waiting for him.
Over nearly a decade, some of his old friends have moved away. Others have passed away, and many relationships have faded because they have not stayed in touch.
That loss can be difficult to accept.
When people first retire abroad, they often picture their home country as something frozen in time. They assume familiar neighborhoods, friendships, and routines will still be waiting whenever they return.
But life continues without them.
Friends retire to different states. Families relocate, neighborhoods change, and people develop new routines.
Even close relationships can become harder to maintain across years of distance.
Paul understands that he cannot simply return to America and pick up his old life where he left off.
He would need to make new friends, find activities, and build another social circle at an age when he would rather enjoy the relationships he already has.
That doesn’t mean making friends after 70 is impossible. Senior centers, volunteering, community groups, and shared interests can help people form meaningful connections.
But rebuilding a social life requires time and effort, especially when someone is also trying to manage housing and financial concerns.
Your New Country Can Become the Center of Your Family Life
Another major reason Paul doesn’t want to leave the Philippines is his wife, May.
He describes a life filled with ordinary pleasures. They spend time together, visit friends, attend celebrations, and enjoy quiet days at home.
Sometimes their happiest moments involve doing almost nothing.
Those peaceful days matter to him just as much as social gatherings.
Moving back to America would not simply mean leaving a country. It could mean disrupting the family life he has built over nine years.
Paul also recognizes that bringing May to America would add another set of questions involving immigration, housing, transportation, healthcare, and living expenses.
His earlier financial estimates considered only his own needs.
A move involving two people would require a different budget and careful planning.
For retirees who marry overseas, this is one of the biggest surprises that can develop over time.
What begins as one person’s retirement decision eventually becomes a family decision.
A spouse may have parents, siblings, friends, and a strong connection to the local community. Moving to another country can mean asking that person to give up many of those relationships.
A retirement plan that works well for one partner may not work equally well for both.
The best place to retire is not always the cheapest country. It is often the place where the people who matter most can build a good life together.
You Can Love Two Countries Without Feeling Fully at Home in Either
Perhaps the most emotional part of Paul’s experience is his sense of belonging.
He loves America and remains proud of being American. He also loves the Philippines, where he has built a home, married, and developed close friendships.
Yet he doesn’t feel completely at home in either place.
In America, he no longer has the familiar life that once made him feel settled. In the Philippines, he remains a foreign resident rather than a Filipino citizen.
He describes himself as being caught between two countries.
This feeling can be difficult to explain to someone who has never lived overseas for an extended period.
In the beginning, being different can feel exciting. New food, traditions, languages, and customs make everyday life interesting.
After many years, however, those differences can take on another meaning.
A foreign resident may speak the local language, understand community traditions, and develop deep friendships while still facing legal or cultural boundaries.
In Paul’s case, he points to his inability to participate in Philippine elections and the fact that he does not enjoy all the rights available to citizens.
That does not mean he has lost his American citizenship or voting rights in U.S. elections. It means his sense of home has become more complicated than his passport suggests.
Long-term residents can feel emotionally attached to a country without holding citizenship there.
This experience shows that retirement satisfaction involves more than affordable housing and pleasant weather.
It also involves identity, acceptance, and feeling that you belong somewhere.
Living Overseas Does Not Automatically Give You Permanent Rights
Many Americans assume that once they have lived abroad for several years, remaining there becomes simple.
But long-term residency and citizenship are different legal arrangements.
A country can welcome foreign retirees while still requiring them to maintain valid immigration status and follow local rules.
The Philippines, for example, offers a Special Resident Retiree’s Visa through the Philippine Retirement Authority.
Eligible retirees can receive long-term residency privileges, including indefinite stay and multiple entry, but the program has specific qualifications and financial requirements.
Other retirees may live in the country under different immigration arrangements.
This distinction matters because a person can build a full life overseas without having exactly the same rights as a citizen.
Residency rules can also affect a retiree’s family, property arrangements, ability to work, and long-term plans.
Before moving, retirees should understand what happens if their circumstances change.
That includes changes involving marriage, income, healthcare needs, and the death of a spouse.
A visa may allow someone to remain in a country for years, but retirees should never assume that living there automatically provides every legal protection they might need.
Medicare Can Become an Unexpected Retirement Expense
Paul’s monthly Social Security figure reveals another issue.
He reports receiving $2,233 after his Medicare Part B deduction.
That means his Medicare premium affects his monthly income even though he lives in the Philippines.
Original Medicare generally does not cover healthcare outside the United States, except in limited circumstances.
For Americans retiring overseas, this can create a difficult choice.
Keeping Medicare Part B may help preserve access to coverage for eligible services when returning to the United States.
However, retirees who spend most of their time abroad may still need separate insurance or savings to cover medical treatment in their new country.
Dropping Part B is not automatically a simple solution. Depending on the person’s circumstances, enrolling again later can result in delayed coverage and a late enrollment penalty.
Healthcare costs also become more significant as retirees age.
Someone who is healthy at 62 may have very different medical needs at 75 or 85.
A good retirement abroad plan must consider routine appointments, medications, specialist care, hospitalization, and possible medical evacuation.
Lower housing expenses are valuable, but they should never be the only reason for choosing a retirement destination.
The Hidden Costs Do Not Disappear Just Because Life Is Cheaper
Paul has found a lifestyle that works financially in the Philippines.
Still, even retirees who enjoy low everyday expenses need to prepare for costs that may not appear in a normal monthly budget.
Healthcare emergencies, visits to family in America, major household repairs, and changes in exchange rates can all affect long-term affordability.
Retiring abroad can also create ongoing administrative responsibilities.
For U.S. citizens, moving overseas generally does not eliminate federal tax filing obligations. Filing requirements still depend on income and other factors, and certain foreign financial accounts may require additional reporting.
These obligations can surprise people who assume that moving away means leaving every American financial responsibility behind.
| Hidden Retirement Issue | Why It Deserves Attention |
|---|---|
| Exchange rate changes | U.S. income may buy less in local currency |
| Healthcare | Medicare generally will not pay for care overseas |
| Visa and residency costs | Immigration requirements may involve fees or financial qualifications |
| Emergency travel | An unexpected flight home can strain savings |
| U.S. tax obligations | Filing and reporting duties may continue |
| Family emergencies | Returning quickly may require money and planning |
The purpose of reviewing these costs isn’t to discourage overseas retirement.
It is to distinguish a low monthly budget from a secure long-term retirement.
A person who saves hundreds of dollars every month by moving abroad may be in a much stronger position financially.
But those savings provide greater protection when some of the money is reserved for problems that may arise years later.
Returning to America Requires More Than Buying a Plane Ticket
One of the most useful lessons from Paul’s experience is the value of keeping a realistic return plan.
Many retirees research their new country’s housing market, visa options, healthcare system, and local living costs before moving.
Far fewer spend the same amount of time studying what returning to America might involve.
They may assume they can simply go back if things don’t work out.
But the cost of rebuilding a life changes over time.
Housing may become more expensive. Personal savings may decline, old accounts may close, and relationships that once provided support may become weaker.
This makes a return plan particularly useful for retirees who expect to live overseas for many years.
Before moving permanently, consider the following questions.
| Question | What to Prepare |
|---|---|
| Where would I live if I returned? | Research actual rental options or possible family arrangements |
| Could my income cover U.S. expenses? | Build a separate return-home budget |
| Would I need a car? | Estimate purchase, insurance, and maintenance costs |
| Is my credit history active? | Check credit reports and maintain useful accounts |
| How would I obtain healthcare? | Review Medicare enrollment and coverage |
| Who could help me settle back in? | Maintain trusted contacts and relationships |
| Could my spouse relocate with me? | Review immigration requirements well before a move |
Having answers doesn’t mean someone must return.
It simply preserves options.
A retiree may spend the rest of their life happily overseas and never need the plan. Yet knowing that a return is financially possible can provide peace of mind.
Paul’s experience shows why those options are easier to protect before they disappear.