
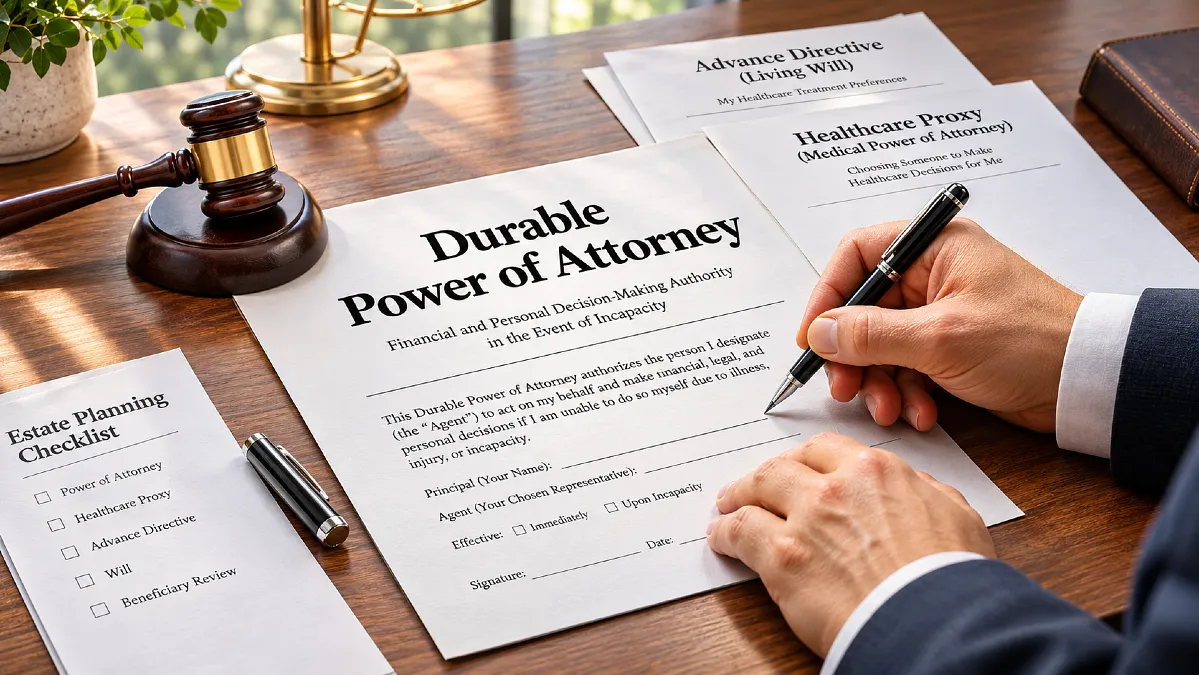
Most people assume their spouse or adult children will handle everything if they become seriously ill. But getting your affairs in order involves more than telling someone where the bank statements are.
A sudden stroke, accident, or memory problem can turn ordinary financial tasks into urgent family problems. The good news is that much of this uncertainty can be reduced in advance.
A few carefully chosen documents, trusted decision-makers, and clear instructions can make a difficult situation easier to manage.
What Happens When Nobody Has the Legal Authority to Help?
Consider a hypothetical 72-year-old retiree who manages the household finances. The mortgage, insurance premiums, credit cards, and utility bills are all paid from accounts in that person’s name.
Then an unexpected medical emergency leaves the retiree unable to communicate or manage money. The family knows which bills need paying, but nobody has been legally authorized to access certain accounts or act on the retiree’s behalf.
The problem is not necessarily a lack of money. It is the lack of authority to use the money for necessary expenses.
Suppose the household has these monthly obligations:
- Housing payment: $1,600
- Insurance premiums: $600
- Utilities and household services: $350
- Care-related expenses: $450
That adds up to $3,000 every month. Two months of unresolved payments would leave $6,000 in obligations needing attention, even if enough savings existed to cover them.
Some payments may continue automatically, and jointly owned accounts may remain accessible to another owner. But accounts held individually, property transactions, or changes to financial arrangements can create obstacles.
Without advance planning, a relative may need to petition a court for authority to manage certain affairs. Depending on state law and the circumstances, this could involve guardianship or conservatorship proceedings.
That process may require legal fees, court filings, medical evidence, and ongoing reporting. More importantly, the family may have less control over who ultimately receives decision-making authority.
Getting Your Affairs in Order Starts With the Right Documents
Many people believe having a will means their legal affairs are covered. However, a will generally addresses what happens after death, not who manages finances or medical decisions during a period of incapacity.
This is why incapacity planning deserves attention alongside traditional estate planning. Several documents serve different purposes, and no single document necessarily covers every situation.
The following comparison shows what each document generally does under U.S. law. Specific requirements and powers depend on the state and the document’s wording.
| Document | Main Purpose | When It Matters |
|---|---|---|
| Durable financial power of attorney | Authorizes someone to handle specified financial matters | During life, including incapacity |
| Health care proxy | Names someone to make medical decisions | When the agent is legally authorized to act |
| Living will or advance directive | Records medical care preferences | When applicable medical decisions arise |
| Medical information authorization | Permits specified health information sharing | When access to private medical information is needed |
| Revocable living trust | Allows a trustee to manage assets held in the trust | During life and potentially after death |
| Last will and testament | Directs certain estate matters and names an executor | After death |
The central distinction is between authority during life and instructions after death. A person can have an excellent will and still leave their family without the authority needed during a medical emergency.
A complete plan considers both situations. It also makes sure the people named in the documents understand their responsibilities.
A Durable Financial Power of Attorney Can Prevent Serious Delays
A financial power of attorney allows a person, known as the principal, to appoint someone else as an agent. The agent can perform financial tasks that the legal document and applicable law authorize.
Depending on the authority granted, those duties might include paying household expenses, handling banking transactions, managing investments, dealing with property, or working with financial professionals. Some actions, such as making gifts or changing beneficiary designations, may require specific authorization.
The word durable is especially important. A durable power of attorney is designed to remain effective even if the principal becomes incapacitated.
Without durability, an ordinary financial power of attorney may cease to operate precisely when the person needs assistance. That could leave the family seeking another legal solution.
Should the Authority Begin Immediately or Only After Incapacity?
Some powers of attorney take effect as soon as they are properly executed. Others, often called springing powers of attorney, become effective only after a specified condition occurs.
A springing arrangement may appeal to someone who wants an additional condition before the agent can act. However, the family may need to obtain medical documentation or satisfy other requirements before financial institutions recognize the authority.
An immediately effective document can reduce that delay, but it also gives the agent substantial authority sooner. The appropriate arrangement depends on trust, personal circumstances, state law, and the safeguards included in the document.
An attorney familiar with the state’s requirements can help define the powers appropriately. The goal is not to surrender financial independence but to establish a reliable backup.
Your Health Care Proxy May Be Just as Important as Your Financial Agent
Medical decisions create a different set of responsibilities. Someone who can pay the mortgage is not necessarily authorized to approve medical treatment.
A health care proxy, sometimes called a health care agent or medical power of attorney, identifies the person who can make health care decisions when legally permitted to do so. Depending on the document and state law, that authority commonly becomes active when the patient cannot make their own decisions.
A separate advance directive or living will can explain treatment preferences. It may address life-sustaining treatment, resuscitation, artificial nutrition, or other important care decisions.
These instructions help the health care agent understand the patient’s wishes. They may also reduce disagreements among relatives who sincerely believe different choices would be best.
For example, one adult child might favor every available treatment, while another believes the parent would prefer comfort-focused care under certain circumstances. Written instructions can provide guidance that does not depend entirely on family memory.
Medical Privacy Also Needs Attention
Medical information is protected by privacy rules, including HIPAA. Family relationships alone do not always provide unrestricted access to a patient’s records.
An authorized health care agent generally has access rights related to the decisions they are legally empowered to make. A separate medical information authorization can also help doctors share appropriate information with selected relatives while the patient remains capable.
Medicare has its own authorization procedures for sharing personal information. Families should confirm which permissions are needed rather than assuming one signed document covers every situation.
The paperwork matters, but the conversation behind it matters just as much. A health care agent should understand the person’s values, treatment preferences, and priorities before an emergency occurs.
Why Being Married or Having Adult Children May Not Be Enough
Marriage creates certain legal rights, and many states recognize family members as potential medical decision-makers when no proxy exists. But those rules do not automatically grant broad authority over every individually owned financial account or legal transaction.
Adult children face similar limits. Being responsible, available, and willing to help does not automatically make someone a legally authorized financial agent.
Several common assumptions can create problems.
| Common Belief | Reality | Better Approach |
|---|---|---|
| My spouse can handle everything | Some authority depends on ownership, documents, and state law | Review financial and medical authorizations |
| My children can access my bank accounts | Family relationships alone do not grant access | Establish appropriate financial authority |
| My will names the person in charge | A will primarily operates after death | Create separate incapacity documents |
| A trusted contact can manage investments | Trusted contacts do not receive trading authority | Arrange authorized account management if needed |
| My power of attorney covers everything | Some agencies require their own appointments or authorizations | Check institution-specific requirements |
This distinction is especially relevant for couples with separate retirement accounts, investments, or property. Even spouses who have managed finances together for decades may discover that ownership and legal authority are not interchangeable.
It is also important to respect the decisions of the person receiving help. Having an illness or needing assistance with paperwork does not automatically mean that person has lost the ability to make their own decisions.
Social Security Has a Rule Families Often Overlook
One of the most important exceptions involves Social Security benefits. The Social Security Administration generally does not treat an ordinary financial power of attorney as an appointment to manage someone’s Social Security payments through its representative payee program.
When Social Security determines that a beneficiary needs someone to manage benefits, the agency appoints a representative payee. This individual or organization must use the benefits for the beneficiary’s needs and follow the program’s recordkeeping requirements.
A spouse, child, or financial agent is not automatically the representative payee. The person must be selected through Social Security’s process.
Fortunately, Social Security offers a planning option called Advance Designation of Representative Payee.
Eligible individuals can name up to three people they would prefer Social Security to consider if a representative payee becomes necessary. The agency evaluates the individuals before making an appointment, so the designation is not a guaranteed selection.
This is particularly useful for retirees who rely on Social Security for housing, groceries, and other recurring expenses. It gives the agency information about the beneficiary’s preferred helpers before a difficult situation develops.
Other agencies may have separate procedures as well. Veterans Affairs has its own fiduciary arrangements, and the IRS uses specific authorizations for tax representation or access to tax information.
These differences show why a complete plan must extend beyond the lawyer’s office. Families need to understand how major institutions recognize authority.
Build a Financial Map Before Someone Needs It
Even with a valid power of attorney, an agent cannot manage an account they do not know exists. Missing information can delay essential tasks and create unnecessary work.
A practical financial inventory should identify the major accounts, recurring obligations, insurance policies, and professionals involved. It does not need to expose every sensitive detail to every family member.
The National Institute on Aging recommends gathering key financial, legal, and health information as part of getting personal affairs in order. The following table offers a starting framework.
| Financial Area | Information to Record | Why It Matters |
|---|---|---|
| Bank accounts | Institution, account type, ownership, contact details | Helps locate available funds |
| Retirement and investments | Provider, account ownership, adviser details | Helps prevent neglected accounts |
| Household bills | Payment amounts, due dates, payment methods | Helps maintain essential services |
| Insurance | Carrier, policy type, premium schedule | Helps avoid missed premiums |
| Property and debts | Deeds, mortgage details, loan contacts | Supports property management |
| Taxes | Tax preparer, recent returns, upcoming deadlines | Helps maintain filing obligations |
The most useful inventory also explains how recurring payments work. An agent should know which bills are automatic, which require approval, and which payments are especially time-sensitive.
For example, missing a streaming subscription payment is usually less urgent than missing homeowners insurance or a property tax deadline. A clear priority list can help someone unfamiliar with the household’s finances make sensible decisions.
Keep the inventory current when accounts are opened, closed, or transferred. A document prepared years ago can become misleading if important financial relationships have changed.
Keep Essential Records Accessible Without Exposing Sensitive Information
One common mistake is storing every important document in a location that nobody else can access. Another is distributing sensitive financial information so widely that privacy and security become concerns.
The better approach is controlled access. Trusted decision-makers should know where relevant records are located and how to obtain them through lawful, secure methods.
A secure home safe, attorney’s office, or protected digital document system may be appropriate. The chosen arrangement should account for emergencies, travel, fire, and the practical ability of the designated person to retrieve the records.
Digital accounts require special attention. Email, utility portals, insurance websites, and financial services may rely on passwords, multifactor authentication, or a phone that only the account holder normally uses.
Instead of sharing passwords casually, consider a reputable password manager with an emergency access feature. Review the services’ rules and applicable laws to determine how a legally authorized person can obtain access.
Another practical step is to make a short emergency information sheet. It can identify the appointed agents, attorney, financial adviser, primary doctor, insurance providers, and the secure location of the main documents without displaying account passwords.
A family member does not necessarily need immediate access to every dollar. They do need a reliable way to identify what requires attention and who has authority to act.
Choose the Right Person, Not Simply the Oldest Child
Selecting an agent can be more difficult than completing the paperwork. Families sometimes assume that the oldest child, nearest relative, or most financially successful person should automatically receive the responsibility.
Those factors may matter, but they do not establish suitability. An agent must be trustworthy, reasonably organized, willing to accept the role, and able to follow another person’s wishes.
A person who is excellent at medical discussions may not enjoy balancing accounts or dealing with banks. Someone skilled with finances may be uncomfortable making difficult treatment decisions.
There is no general requirement that the same person hold both roles. Appointing separate financial and health care agents may be appropriate when their abilities and availability differ.
Always Consider a Backup
A first-choice agent may become ill, move away, or decide they cannot serve. Naming a successor agent can help prevent the entire arrangement from becoming ineffective.
The backup should understand that their authority depends on the document and circumstances. They also need to know how to obtain the documents if their role becomes active.
Some families consider appointing multiple people to serve together. That can provide shared oversight, but it can also create delays if both signatures are required or disagreements prevent action.
An attorney can explain how joint agents, independent agents, and successor agents work under local law. The simplest structure that provides appropriate protection is often easier for institutions and family members to administer.
Protect Your Money From Misuse by an Appointed Helper
Giving someone financial authority creates risk as well as convenience. A durable power of attorney may permit significant transactions without the same routine oversight that a court-appointed arrangement requires.
The Consumer Financial Protection Bureau emphasizes that people managing another person’s money have fiduciary responsibilities. These include acting in the person’s interest, handling property carefully, keeping funds separate, and maintaining accurate records.
An agent should not treat access to someone else’s checking account as permission to spend freely. Even well-intentioned decisions can create problems if they benefit the agent or conflict with the principal’s instructions.
Families can consider several safeguards.
Requiring periodic financial reports to an independent trusted person may improve accountability. The document can also address whether the agent may make gifts, change beneficiary arrangements, or transfer property.
A financial professional may be able to help monitor unusual transactions, while brokerage firms often provide a trusted contact option. A trusted contact can help a firm respond to concerns, but cannot automatically make investments or withdraw funds.
It is also worth reconsidering the assumption that a helper must become a joint owner of a bank account. Joint ownership can create withdrawal rights and inheritance consequences that go far beyond assistance with bill paying.
A carefully structured power of attorney or an appropriate bank agency arrangement may meet the need without changing ownership. The correct solution depends on the person’s goals and the options available.
A Living Trust May Help, but It Does Not Replace Every Document
A revocable living trust is another tool families sometimes consider. It can allow a successor trustee to manage assets held in the trust when the original trustee can no longer serve.
This may be particularly useful when an estate includes multiple properties or assets requiring ongoing management. It can also provide a framework for managing certain trust assets after death.
However, a trust generally governs assets that are actually held by the trust. Creating a trust document without transferring the intended assets into it may leave important property outside the arrangement.
A living trust also does not automatically authorize medical decisions. A health care proxy and other advance care documents remain separate considerations.
Similarly, a will and beneficiary designations address what happens to property after death. They should be reviewed alongside incapacity documents, but their primary purpose is different.
Financial power of attorney authority generally ends at the principal’s death. At that point, administration of estate assets may pass to an executor, administrator, surviving owner, or trustee, depending on the property and applicable law.
The main lesson is that estate planning and incapacity planning work together. One should not be mistaken for the other.
Four Paperwork Problems That Can Derail a Good Plan
Signing legal documents is an important milestone, but it is not the end of the process. A plan can still fail in practice if documents are hard to locate, poorly matched to the person’s assets, or unfamiliar to the institutions that must recognize them.
Banks and other financial firms may need to review a power of attorney before permitting transactions. Although state laws often require institutions to accept valid documents, additional verification or legitimate concerns about the authority can delay access.
The following situations deserve attention before an emergency occurs.
| Potential Problem | What Can Go Wrong | Preventive Step |
|---|---|---|
| Missing original documents | An agent may struggle to prove authority | Confirm where originals and accepted copies are kept |
| Outdated appointments | A named agent may no longer be available | Review agents and successors regularly |
| Unclear powers | An institution may question a requested transaction | Review the scope of authority with an attorney |
| Unknown accounts | Important assets or bills may be overlooked | Maintain an updated financial inventory |
| Uninformed decision-maker | The agent may not know the person’s wishes | Discuss responsibilities and preferences in advance |
A useful test is to contact the main bank or brokerage while the account holder is still able to participate. Ask about its procedures for recognizing a financial agent and any additional documentation that might be required.
This is also a good opportunity to ask insurance providers and medical offices about their authorization procedures. Finding an administrative problem early is much easier than discovering it during a hospitalization.