
Retirement changes the way people look at their savings. A falling stock market suddenly feels more personal when there is no regular paycheck coming in, especially when everyday bills still need to be paid.
That uncertainty can push retirees into costly decisions. Some sell investments during market declines, while others keep too much money in cash because they are afraid to spend what they have saved.
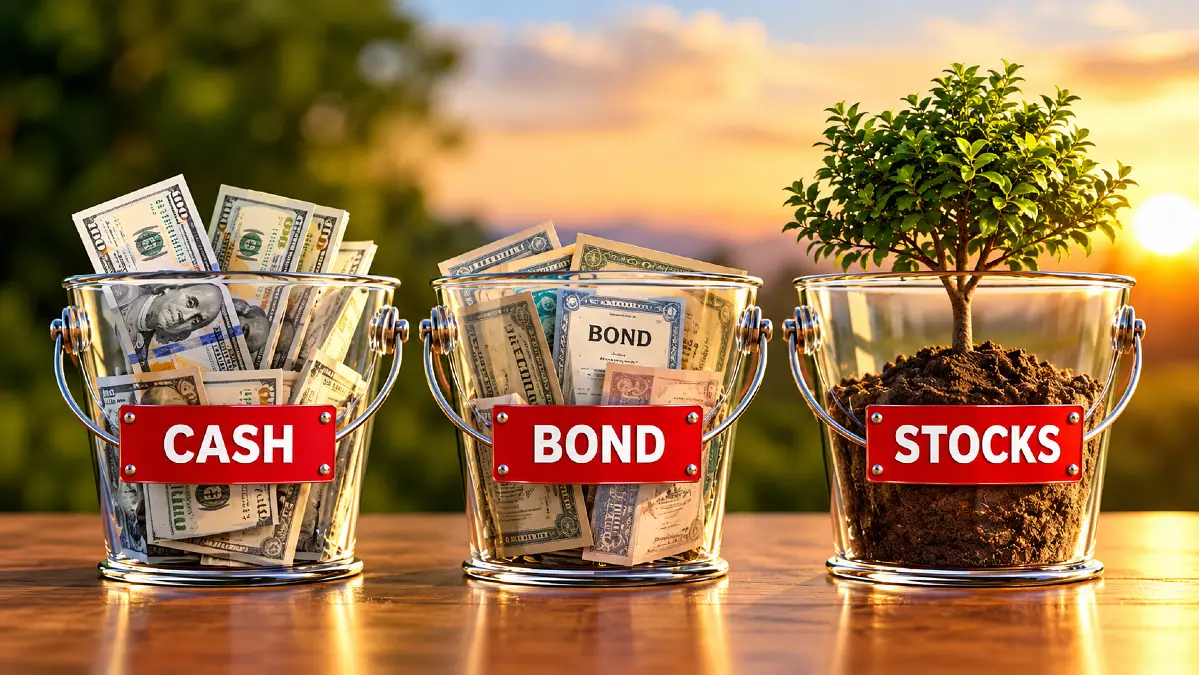
A retirement bucket strategy offers another approach. By dividing savings into three pots for immediate expenses, medium-term needs, and long-term growth, retirees can give every dollar a clearer purpose.
Why Retirement Savings Suddenly Feel Harder to Spend
During working years, market declines are often easier to tolerate. A paycheck continues arriving, retirement contributions may continue, and there is usually time to recover from investment losses.
Retirement changes that relationship with money. Instead of adding to savings every month, people begin withdrawing from accounts they spent decades building.
Consider a hypothetical retiree with $600,000 invested. If the portfolio loses 20% of its value, the balance falls to $480,000 before accounting for withdrawals.
That $120,000 decline can feel frightening, even if the retiree has enough dependable income to cover most living expenses. The emotional reaction may be stronger than the immediate financial problem.
The real concern is not simply losing money on paper. It is needing to sell investments while their prices are temporarily depressed.
A retiree who understands where the next two years of spending money will come from may find it easier to avoid rushed decisions. That is the basic thinking behind the three-bucket retirement strategy.
The Three-Bucket Retirement Strategy Gives Every Dollar a Job
The bucket strategy divides retirement investments according to when the money will likely be needed. Instead of treating a portfolio as one large balance, retirees organize it into cash, bonds, and stocks.
Each category has a different responsibility. Cash provides immediate access, bonds support future withdrawals, and stocks offer the possibility of long-term growth.
Financial researchers and retirement planners commonly describe this approach as time segmentation. The purpose is to match investment risk with the time available before the money must be spent.
| Retirement Pot | Main Purpose | Typical Time Horizon | Common Investments |
|---|---|---|---|
| Pot 1: Cash | Cover immediate withdrawals | Next 1–2 years | Savings, Treasury bills, money market holdings |
| Pot 2: Bonds | Support medium-term spending | Following 5–8 years | High-quality bonds and bond funds |
| Pot 3: Stocks | Support future growth | Longer-term needs | Diversified stock funds |
These time periods are planning guidelines rather than fixed rules. Some retirees need more short-term reserves, while others can reasonably hold less.
The pots also do not require three separate financial accounts. A retiree can organize investments this way inside existing IRAs, brokerage accounts, and workplace retirement plans.
The important distinction is knowing which investments serve which spending needs.
Pot One: Cash Covers the Bills That Cannot Wait
The first pot is designed for money that may be needed soon. This includes the portion of household spending not covered by Social Security, pensions, or other dependable income.
A common starting point is one to two years of planned portfolio withdrawals. This is different from keeping two years of total household expenses in cash.
Suppose a retiree spends $5,000 monthly but receives $3,500 from Social Security and a pension. The retirement portfolio only needs to supply the remaining $1,500 per month.
That creates an annual portfolio withdrawal need of $18,000. Two years of planned withdrawals would require $36,000 in the cash pot, before allowing for changes in spending or taxes.
This distinction can prevent retirees from keeping far more money in cash than necessary.
Where should the cash be kept?
High-yield savings accounts, insured bank deposits, short-term Treasury bills, and appropriate money market holdings may all play a role. The best choice depends on accessibility, safety, account rules, and how soon the money is needed.
Bank deposits at FDIC-insured institutions generally receive coverage up to $250,000 per depositor, per insured bank, per ownership category. Money market mutual funds are investments, however, and do not receive FDIC deposit insurance.
Cash protects against having to sell investments at an inconvenient time. It does not eliminate inflation risk, and holding excessive amounts may reduce long-term growth.
A separate emergency reserve may also be appropriate for major home repairs, medical expenses, or other unpredictable bills.
Pot Two: Bonds Provide a Middle Ground
The second pot supports spending needs that are too far away for everyday cash but too close to rely entirely on stocks.
High-quality bonds are often used for this purpose because they may provide income and generally have less price volatility than stocks. They can also offer another source of withdrawals during prolonged stock market weakness.
Consider a retiree who needs $25,000 annually from investments. Setting aside six years of that amount would create a $150,000 intermediate-term bond pot.
That does not mean the retiree must withdraw exactly $25,000 from bonds every year. The bond pot is a reserve that can help support future withdrawals as circumstances change.
Treasury securities, investment-grade bonds, and diversified short- or intermediate-term bond funds are common possibilities. Their suitability depends on credit quality, maturity, interest-rate sensitivity, and the retiree’s overall portfolio.
Bonds are not the same as cash.
Bond prices can fall when interest rates rise. Longer-term bonds generally have greater exposure to these price changes, while bonds issued by financially weaker borrowers carry additional default risk.
Individual high-quality bonds held to maturity and bond funds also behave differently. A bond fund has no single maturity date that guarantees the investor will recover the original purchase amount.
The second pot should therefore be built around quality and appropriate maturity, rather than simply choosing whichever investment offers the highest yield.
Pot Three: Stocks Give Retirement Savings Room to Grow
The third pot contains investments intended for spending much later in retirement. Its main purpose is to provide long-term growth potential.
This matters because retirement may last 20 or 30 years, and household expenses are unlikely to remain unchanged throughout that period.
Stocks have historically offered stronger long-term growth potential than cash and high-quality bonds, although they also bring greater price volatility. Some periods of market weakness can last for years.
A diversified stock portfolio might include broad U.S. and international stock funds rather than concentrating retirement savings in a few companies.
The goal is not to find the next winning stock. It is to maintain exposure to businesses and economic growth while reducing the risk associated with relying on individual companies.
The greatest advantage of the third pot is time. Money that will not be needed for many years has more opportunity to recover from market declines.
Still, no stock allocation guarantees positive returns over a particular decade. The amount assigned to stocks should reflect the household’s spending needs, ability to tolerate losses, and available income.
Start With the Retirement Income Gap, Not the Account Balance
One of the most useful parts of the bucket strategy is that it begins with spending rather than portfolio size.
A retiree with $800,000 invested and a large pension may need less cash than someone with the same investment balance who depends almost entirely on withdrawals.
Consider a hypothetical retired couple with the following annual budget. The figures are illustrative and assume all income, spending, and estimated taxes have been included consistently.
| Budget Item | Annual Amount | Monthly Equivalent |
|---|---|---|
| Household expenses, including estimated taxes | $72,000 | $6,000 |
| Social Security and pension income | $42,000 | $3,500 |
| Needed from investments | $30,000 | $2,500 |
| Cash for two years of withdrawals | $60,000 | 24 months of withdrawals |
The couple needs $30,000 annually from their portfolio, not $72,000. This difference is the starting point for calculating their retirement buckets.
It also shows why two households with identical savings can require very different portfolios.
The $30,000 withdrawal need must still be checked against their savings and expected retirement length. Dividing money into buckets does not make an otherwise unsustainable withdrawal amount sustainable.
For someone with $750,000 in savings, a $30,000 initial annual withdrawal equals 4% of the portfolio. That is a familiar retirement planning benchmark, but it is not a guarantee that the money will last.
What a $750,000 Retirement Portfolio Could Look Like
Using the hypothetical couple’s $30,000 annual portfolio withdrawal need, the next step is assigning money to each pot.
For this example, assume the couple chooses two years of withdrawals in cash and another eight years in high-quality bonds. The remaining investments are available for longer-term growth.
| Retirement Pot | Starting Amount | Share of Portfolio | Intended Role |
|---|---|---|---|
| Cash | $60,000 | 8% | Next 2 years |
| Bonds | $240,000 | 32% | Following 8 years |
| Stocks | $450,000 | 60% | Longer-term growth |
| Total | $750,000 | 100% | Complete portfolio |
This produces a portfolio with 60% in stocks, 32% in bonds, and 8% in cash.
The couple can immediately identify money intended for near-term withdrawals without assuming that every dollar must be sold in a rigid sequence.
However, the $300,000 assigned to cash and bonds is not guaranteed to fund exactly ten years of spending. Bond values can fluctuate, inflation can raise withdrawals, and both categories may earn interest or experience changes in value.
The allocation is also not suitable for everyone. A retiree who cannot tolerate a substantial stock decline may need less stock exposure, while someone with strong guaranteed income may be comfortable holding more.
What makes the strategy useful is the connection between spending needs and investment choices, rather than any particular percentage.
Why Selling Stocks During a Market Crash Can Be So Expensive
Financial planners call one of retirement’s biggest investment dangers sequence-of-returns risk. It means the order in which good and bad investment returns occur can affect how long savings last when regular withdrawals are being made.
A market decline early in retirement can be especially damaging because money is being withdrawn at the same time investments are losing value.
Consider a simplified example involving a stock fund with a share price of $100. A retiree who needs $30,000 would have to sell 300 shares.
If the price falls 25% to $75, the retiree would have to sell 400 shares to receive that same $30,000.
That means selling one-third more shares after the decline. Those additional shares will no longer participate in any later market recovery.
This is why two retirees can experience similar long-term investment returns but end up with different balances when their withdrawals occur alongside different market conditions.
The three-bucket strategy attempts to reduce the pressure to sell depressed stocks. Cash can fund immediate needs, while appropriate bond holdings may provide another source of withdrawals.
It does not eliminate investment losses or guarantee better results than a conventional diversified portfolio. Its benefit depends on the asset allocation, withdrawal decisions, spending flexibility, and future market performance.
How Retirees Refill Their Three Pots Without Selling at the Wrong Time
The bucket strategy becomes more complicated after the first year. Once cash has been spent, retirees must decide how and when to replenish it.
A common mistake is assuming money must always move automatically from stocks into bonds and then into cash. That rigid process can force investment sales at unfavorable prices.
A more flexible approach involves reviewing available cash, investment income, market performance, and the overall portfolio allocation.
| Market Situation | Possible Action | Important Tradeoff |
|---|---|---|
| Stocks have risen strongly | Trim stocks that exceed the target allocation | May trigger taxes |
| Stocks have fallen sharply | Use existing cash reserves | Cash reserve declines |
| Bonds have performed reasonably well | Consider bond maturities or selective sales | Bond sales may still produce losses |
| Stocks and bonds are both weak | Review spending and withdrawal flexibility | Reserves may need longer to recover |
| Cash falls below its target | Replenish when practical | Avoid automatic sales at poor prices |
The annual review matters more than reacting to every market headline. It allows retirees to consider the entire portfolio before deciding where withdrawals should come from.
For example, suppose the hypothetical couple’s $450,000 stock pot grows substantially during a strong market year. If stocks now represent more than the couple’s intended portfolio allocation, selling some appreciated holdings may restore balance and replenish cash.
During a severe stock downturn, the couple may instead rely on existing cash and appropriate bond proceeds. They might also postpone a large discretionary purchase to reduce withdrawals.
Interest, dividends, and maturing bonds can help provide cash, but they are not free additional returns. They are part of the portfolio’s total investment results.
The aim is to maintain an appropriate overall investment mix while funding retirement expenses.
Inflation Can Quietly Change the Size of Every Bucket
A cash reserve that covers two years of withdrawals today may not cover the same amount of spending ten years from now.
Inflation gradually raises the cost of groceries, insurance, utilities, home maintenance, and other expenses. Even moderate annual increases become meaningful over a long retirement.
Assume a retiree needs $30,000 annually from investments today. With inflation averaging 3% per year, that same purchasing power would require approximately $40,300 annually after ten years.
That is roughly $10,300 more per year, even without an improvement in lifestyle.
This is one reason holding the entire retirement portfolio in cash can be risky over the long term. Account balances may appear stable while their purchasing power declines.
Stocks provide one possible source of long-term growth, although they are not a perfect inflation hedge. Some bonds, including Treasury Inflation-Protected Securities, can also help address inflation risk.
Retirees should revisit their bucket targets as spending changes. A withdrawal plan built around expenses from five years ago may no longer reflect the household’s needs.
Five Mistakes That Can Make the Bucket Strategy Less Effective
The three-bucket system is straightforward in principle, but its implementation still requires judgment.
Keeping Too Much Money in Cash
A larger cash reserve may feel comfortable, especially after experiencing a market decline. However, excessive cash holdings can reduce the portfolio’s potential for long-term growth.
The appropriate amount depends on actual withdrawals, dependable income, and risk tolerance. More cash is not automatically better.
Treating Bonds as Completely Safe
High-quality bonds can reduce some investment risks without eliminating all of them. Bond funds can decline in value, particularly when interest rates rise sharply.
Investors should consider duration, credit quality, expenses, and the likelihood of needing to sell before maturity.
Refilling Cash at Any Cost
Selling stocks immediately after a major decline simply to restore a preferred cash balance may defeat part of the strategy’s purpose.
It can be reasonable to let the cash reserve temporarily decline, provided the household has a plan for spending, available bonds, and overall portfolio risk.
Ignoring the Overall Investment Mix
Three buckets can create a false sense of diversification if the underlying investments are poorly selected.
A retiree might own multiple stock funds that all hold similar large companies. Separating them into different accounts does not eliminate that concentration.
The combined portfolio still needs appropriate diversification across asset classes and, where suitable, geographic markets.
Assuming Buckets Solve an Overspending Problem
A retiree who withdraws too much money every year can still exhaust retirement savings, even with a carefully designed bucket system.
The withdrawal amount must remain realistic in relation to portfolio size, expected retirement length, taxes, inflation, and investment performance.
Taxes Can Change Which Pot Should Be Used First
Retirement investments are often spread across traditional IRAs, Roth IRAs, 401(k) plans, and taxable brokerage accounts.
Those accounts do not all follow the same tax rules. This means a decision about which investment to sell is not always the same as deciding which account should distribute the money.
For example, selling an investment inside a traditional IRA generally does not immediately create a separate capital gains tax. However, money distributed from that IRA is generally taxable as ordinary income, subject to applicable exceptions.
Qualified Roth IRA withdrawals are generally tax-free. Selling appreciated investments in a taxable brokerage account may create capital gains taxes, depending on the holdings and circumstances.
Required minimum distributions, or RMDs, add another consideration. Under applicable IRS rules, certain retirement account owners must take annual minimum withdrawals after reaching the relevant starting age.
A retiree cannot ignore those requirements simply because the cash bucket is located elsewhere.
Large taxable withdrawals can also affect the taxation of Social Security benefits or Medicare income-related premiums, depending on the household’s circumstances.
The practical lesson is that retirees should coordinate their investment buckets with account types and tax planning. Moving money between investment categories does not necessarily require moving it between account registrations.
The Best Three-Bucket Plan Is Not the Same for Every Retiree
A recently retired 62-year-old may need savings to support several decades of spending. Someone retiring at 76 may have different income needs, health considerations, and investment priorities.
Portfolio size alone cannot determine the right strategy. Dependable income, household spending, investment risk, and expected future needs all matter.
For retirees with strong pension income, the amount needed from investments may be relatively small. A smaller cash reserve could still cover one or two years of actual portfolio withdrawals.
For retirees relying heavily on savings, withdrawals may represent a larger share of their portfolios. They may need more careful spending controls and a stronger plan for managing market declines.
For retirees with limited savings, holding enough cash and bonds for many years of withdrawals may leave too little invested for future growth. A simpler, diversified approach with an emergency reserve may be more practical.
Couples also need to consider how income and expenses could change after the death of a spouse. Survivor benefits, taxes, housing costs, and medical spending can alter the household budget substantially.
The retirement bucket strategy is a framework for making decisions, not a formula that produces the same answer for every household.