
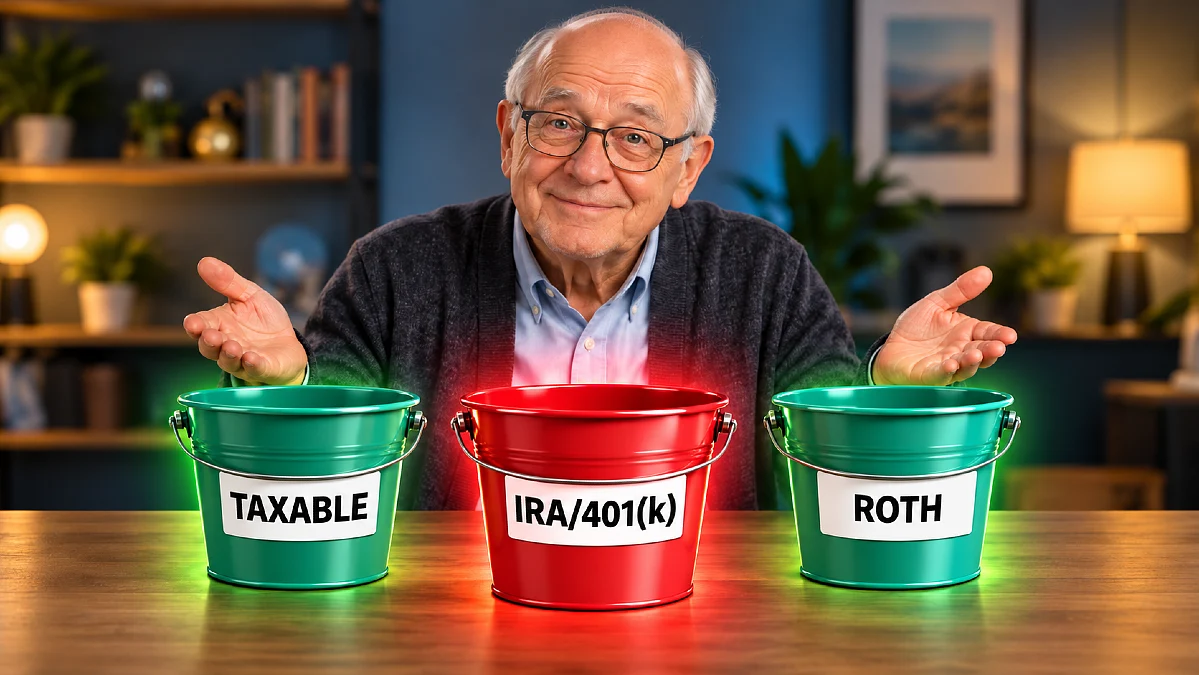
Retirement changes how money enters your bank account, but it does not remove the need to manage taxes. Choosing the wrong retirement account for a withdrawal can increase your tax bill, make more of your Social Security taxable, and even raise your Medicare premiums.
The order you draw from taxable, tax-deferred, and Roth accounts can make a meaningful difference over 20 or 30 years of retirement. Yet many retirees simply withdraw from whichever account has the largest balance without considering what that decision might cost later.
A smarter approach usually involves combining withdrawals from different accounts rather than draining one account at a time. The goal is to keep taxes manageable today while avoiding larger tax problems in your 70s and 80s.
The Three Types of Retirement Accounts Work Differently
Before deciding where to withdraw money, you need to understand how each account is taxed. Two accounts holding the same investment can produce very different tax bills when you take money out.
Most retirees have some combination of taxable investment accounts, traditional retirement accounts, and Roth accounts. Each serves a different purpose in a retirement income plan.
| Account Type | Common Examples | Tax Treatment When Withdrawing |
|---|---|---|
| Taxable | Brokerage accounts, investment accounts | Generally, tax applies to realized gains, not the entire amount withdrawn |
| Tax-deferred | Traditional IRA, 401(k), 403(b) | Withdrawals of previously untaxed money generally count as ordinary income |
| Roth | Roth IRA, Roth 401(k) | Qualified withdrawals are tax-free |
A taxable brokerage account can provide flexibility because part of the money you receive may represent your original investment. That portion is generally not taxed again when you sell investments.
Traditional retirement accounts work differently because most withdrawals are included in ordinary taxable income. Roth accounts offer another option because qualified distributions generally do not increase your federal taxable income.
The challenge is knowing how to combine these accounts without creating an unnecessary tax burden.
The Withdrawal Order That Often Makes the Most Sense
For many retirees, a useful starting point is spending from cash and taxable accounts, taking controlled withdrawals from traditional retirement accounts, and preserving Roth savings for later years.
However, this is not a strict order that everyone should follow. Retirees often benefit from using more than one account during the same tax year.
Here is how the general strategy works.
| Priority | Withdrawal Strategy | Main Purpose |
|---|---|---|
| First | Use available cash and taxable investments | Cover spending while managing realized gains |
| Alongside taxable withdrawals | Take planned traditional IRA or 401(k) withdrawals | Use available lower tax brackets and reduce future tax-deferred balances |
| When appropriate | Convert some traditional retirement savings to Roth | Potentially reduce future required withdrawals |
| Selectively | Use qualified Roth withdrawals | Cover expenses without increasing taxable income |
| Once required | Take required minimum distributions | Meet IRS withdrawal rules |
The goal is not to pay the least possible tax every single year. It is to reduce your total tax burden over retirement, including the taxes you may owe much later.
Someone who pays very little tax at 65 could face substantially larger bills at 75 if traditional retirement savings continue growing and required withdrawals begin.
That is why careful planning during the early retirement years can be valuable.
Why Drawing Everything From Your Traditional IRA First Can Backfire
Imagine a retiree who needs another $40,000 to cover annual living expenses. Taking the entire amount from a traditional IRA may look simple because the money is readily available.
However, if that IRA contains only previously untaxed contributions and earnings, the withdrawal generally adds $40,000 to ordinary income. Depending on the retiree’s situation, that additional income could create several problems.
It might move part of their income into a higher federal tax bracket, increase the taxable portion of Social Security benefits, or affect future Medicare premiums. A large withdrawal can also reduce the amount left invested for later years.
Using taxable investments or qualified Roth withdrawals for part of that $40,000 may produce a different result. The best combination depends on the retiree’s existing income, investment gains, deductions, and future tax expectations.
Taking money from a traditional IRA is not automatically a mistake. The problem is making withdrawals without considering how much taxable income they create.
Using Taxable Accounts First Can Give You More Flexibility
Taxable brokerage accounts are often useful during the first years of retirement. They allow retirees to raise cash without necessarily treating the entire withdrawal as ordinary income.
Suppose you sell $20,000 worth of investments that originally cost $15,000. Your gain is $5,000, meaning the original $15,000 generally comes back without an additional federal capital gains tax.
If you had withdrawn the same $20,000 from a fully pretax traditional IRA, the entire amount would generally count as ordinary income.
Long-term capital gains also receive different tax treatment from ordinary income. Depending on total taxable income, they may qualify for federal rates of 0%, 15%, or 20%.
For 2026, married couples filing jointly can qualify for the 0% long-term capital gains rate on gains falling within the first $98,900 of total taxable income. Single filers have a threshold of $49,450.
That does not mean a married couple can automatically realize $98,900 in tax-free gains. Other taxable income uses part of that income range, and some investment income may face additional taxes.
The biggest advantage of a taxable account is the ability to control which investments you sell and when you realize gains. Selling investments with smaller gains can sometimes provide spending money while keeping taxable income lower.
However, taxable gains can still affect Social Security taxation and Medicare income calculations, even when the gains qualify for a 0% federal capital gains rate.
Your 60s May Be the Best Time to Reduce Future IRA Taxes
The years between leaving work and starting required minimum distributions can provide an opportunity for retirement tax planning. Income may be lower during this period because wages have stopped and Social Security has not yet begun.
That creates a chance to withdraw money from traditional retirement accounts at potentially lower tax rates. Some retirees also use these years to convert part of their traditional IRA savings into Roth accounts.
A Roth conversion moves money from a traditional retirement account into a Roth account. Previously untaxed amounts converted are generally included in ordinary income for that year.
The immediate tax bill may seem unpleasant, but the conversion can reduce the amount remaining in tax-deferred accounts. That may lead to smaller required withdrawals later.
For example, someone expecting to pay a 24% marginal tax rate in retirement might find it worthwhile to convert some traditional IRA savings while those dollars fall into a 12% bracket. However, the comparison must include other taxes, lost deductions, and Medicare effects.
Here are the relevant federal income tax brackets for married couples filing jointly in 2026.
| Federal Tax Rate | Married Filing Jointly: Taxable Income |
|---|---|
| 10% | $0–$24,800 |
| 12% | Over $24,800–$100,800 |
| 22% | Over $100,800–$211,400 |
| 24% | Over $211,400–$403,550 |
These are marginal brackets, meaning only the income within each range is taxed at that rate. The taxable-income amounts are calculated after applicable deductions.
For 2026, the standard deduction for married couples filing jointly is $32,200, with additional deductions potentially available based on age and other qualifications.
An enhanced senior deduction of up to $6,000 per eligible person is also available for 2025 through 2028, subject to income limits. A large Roth conversion could reduce eligibility for that deduction.
This is why filling a tax bracket with Roth conversions is a planning technique rather than an automatic rule. The conversion amount must fit the retiree’s complete tax picture.
The Social Security Tax Trap Can Make Withdrawals More Expensive
One of the biggest surprises for retirees is discovering that taking money from an IRA can make more of their Social Security benefits taxable.
The federal government uses a calculation commonly called combined income to determine how much Social Security may be subject to federal income tax.
Combined income generally includes adjusted gross income, certain tax-exempt interest, and half of annual Social Security benefits.
The income thresholds have remained unchanged for decades, which means inflation and other retirement income can push more people above them.
| Filing Status | First Combined Income Threshold | Second Threshold |
|---|---|---|
| Single | $25,000 | $34,000 |
| Married filing jointly | $32,000 | $44,000 |
Above the first threshold, up to 50% of Social Security benefits may become taxable. Above the second threshold, up to 85% may be included in taxable income.
It is worth emphasizing that this does not mean retirees pay an 85% tax rate. It means up to 85% of their Social Security benefits may be subject to their applicable income tax rates.
Consider a couple already receiving Social Security who decides to withdraw another $20,000 from a traditional IRA. That withdrawal may increase their adjusted gross income while also causing additional Social Security benefits to become taxable.
As a result, their taxable income can increase by more than the amount of the IRA withdrawal alone. The effective tax cost may therefore be higher than their ordinary marginal tax bracket suggests.
This is sometimes called the Social Security tax torpedo. It is one reason retirees should calculate the effect of additional withdrawals rather than assuming every IRA dollar creates the same tax cost.
Medicare Premiums Can Rise Two Years After a Large Withdrawal
Medicare presents another retirement tax planning problem because higher income can increase monthly premiums.
The Income-Related Monthly Adjustment Amount, commonly called IRMAA, applies additional charges to Medicare Part B and Part D premiums for people whose income exceeds certain limits.
Medicare generally uses tax information from two years earlier when calculating these adjustments. For example, 2026 IRMAA amounts ordinarily reflect income reported for 2024.
Here are the initial 2026 income thresholds.
| 2024 Modified AGI | Single Filer | Married Filing Jointly |
|---|---|---|
| Standard premium tier | $109,000 or less | $218,000 or less |
| First higher premium tier | Over $109,000 | Over $218,000 |
| Second higher premium tier | Over $137,000 | Over $274,000 |
For 2026, the standard Medicare Part B premium is $202.90 per month. The first higher-income tier increases that premium to $284.10 per month, with an additional Part D adjustment also applying where relevant.
The problem is that crossing an IRMAA threshold can increase the entire monthly premium rather than applying a small additional charge only to the income above the limit.
A large IRA withdrawal, investment gain, or Roth conversion may therefore create Medicare costs that appear later. Retirees approaching age 65 should consider this before creating unusually high taxable income in their early 60s.
There is no rule saying Roth conversions must stop at age 63. They can still make sense later, but the two-year Medicare lookback becomes part of the calculation.
Retirement or a substantial reduction in work income can sometimes qualify someone to request a new IRMAA determination based on a more recent income year. A voluntary Roth conversion by itself is not generally one of the qualifying life-changing events.
Required Minimum Distributions Can Change Everything in Your 70s
Traditional retirement accounts generally cannot remain untouched indefinitely. Once retirees reach the applicable age, the IRS requires minimum annual withdrawals from accounts such as traditional IRAs and 401(k)s.
For many retirees, required minimum distributions begin at age 73. Under current law, the starting age increases to 75 for people born in 1960 or later.
These withdrawals are calculated using account balances and IRS life expectancy tables. Larger traditional retirement account balances generally produce larger required distributions.
Imagine a retiree who has $1 million in a traditional IRA when required distributions begin. Even if that person needs relatively little spending money, the IRS may require a substantial withdrawal each year.
Those distributions can add to ordinary income, increase the taxable portion of Social Security, and potentially raise Medicare premiums.
This is why reducing traditional IRA balances during lower-income retirement years can be useful. Retirees may have more control over the amount they withdraw before the required distributions begin.
After RMDs start, the withdrawal sequence changes. The required amount must be satisfied, even if the retiree would prefer using taxable investments or Roth savings.
A required minimum distribution cannot be converted into a Roth IRA. Any additional eligible traditional IRA funds may still be converted, but the RMD obligation must be handled first.
A Couple With $1.5 Million Shows How the Strategy Can Work
Consider Tom and Linda, a married couple who recently retired. Tom is 67, Linda is 65, and they have spent decades building savings across three types of accounts.
They want to spend about $90,000 per year after taxes. They do not have a pension, but they expect to receive Social Security benefits.
Here is their retirement picture.
| Financial Detail | Amount |
|---|---|
| Tom’s age | 67 |
| Linda’s age | 65 |
| Annual after-tax spending goal | $90,000 |
| Taxable brokerage account | $500,000 |
| Traditional IRAs and 401(k)s | $700,000 |
| Roth IRAs | $300,000 |
| Total retirement investments | $1,500,000 |
| Combined annual Social Security if both claimed now | $48,000 |
Tom and Linda have enough different account types to create flexibility. But the way they withdraw from those accounts could affect their lifetime tax burden.
Their situation can be divided into two important retirement periods.
Phase One: Before Both Social Security Benefits Begin
Tom considers delaying his Social Security benefit until age 70, while Linda plans to claim around her full retirement age.
Delaying benefits can increase future monthly payments, although whether that is the best choice depends on health, life expectancy, survivor needs, and available savings.
During these early retirement years, Tom and Linda would need to fund much of their spending from investments.
Instead of taking every dollar from their traditional accounts, they could use available cash and taxable brokerage assets to cover much of their living expenses.
At the same time, they could consider controlled traditional IRA withdrawals or Roth conversions during years when their taxable income is relatively low.
They might decide to fill part of the 12% federal bracket or use a carefully calculated amount in the 22% bracket. That decision would depend on their projected future taxes and other income-related costs.
Their Roth IRA savings could remain invested, giving them another source of flexible income later.
The goal would be to meet the $90,000 annual after-tax spending target while gradually managing their $700,000 tax-deferred balance.
Phase Two: After Social Security Benefits Begin
When Tom and Linda begin receiving Social Security, their annual income picture changes.
Benefits now cover part of their spending needs, meaning they may need to withdraw less from investments. However, traditional IRA withdrawals can also cause more of their Social Security benefits to become taxable.
That makes the withdrawal decision more sensitive to tax thresholds.
They could continue using taxable investments for part of their expenses while making smaller IRA withdrawals when appropriate. Qualified Roth withdrawals could help cover occasional larger expenses without increasing their taxable income.
Once their required minimum distributions begin, those amounts must be incorporated into the plan before choosing additional withdrawals.
By managing tax-deferred savings during earlier years, Tom and Linda may be able to reduce future required withdrawals and preserve more flexibility.
There is no guarantee this strategy will save them a particular amount. A reliable comparison would require projections of investment returns, inflation, taxes, Social Security benefits, longevity, and spending.
Still, the example illustrates an important point: the right withdrawal order can change as retirement progresses, even when the underlying accounts remain the same.
Why Roth Savings Are Often Worth Protecting Until Later
Roth accounts can be especially useful in retirement because qualified withdrawals generally do not increase federal taxable income.
For a Roth IRA, qualified treatment generally requires satisfying the five-year rule and meeting an additional condition, commonly reaching age 59½. Different rules may apply to nonqualified withdrawals and converted amounts.
This flexibility can matter when retirees face large expenses that do not fit their regular budget.
A new roof, expensive vehicle repair, major trip, or financial gift to family might require tens of thousands of dollars. Funding those costs entirely from a traditional IRA could create a large increase in taxable income.
A qualified Roth withdrawal may help avoid that increase. It can also help retirees stay below certain Medicare income thresholds.
Another advantage is that original Roth IRA owners are not required to take minimum distributions during their lifetimes. The same lifetime RMD exemption also applies to designated Roth accounts in employer plans under current rules.
However, keeping Roth savings until last is not always the best decision.
Someone with a very large Roth balance but limited taxable assets may benefit from spending some Roth funds earlier. Roth withdrawals may also make sense in years when additional traditional IRA income would create unusually high taxes.
The question is not whether Roth money should remain untouched forever. It is whether spending those dollars now is more valuable than preserving them for future flexibility.