
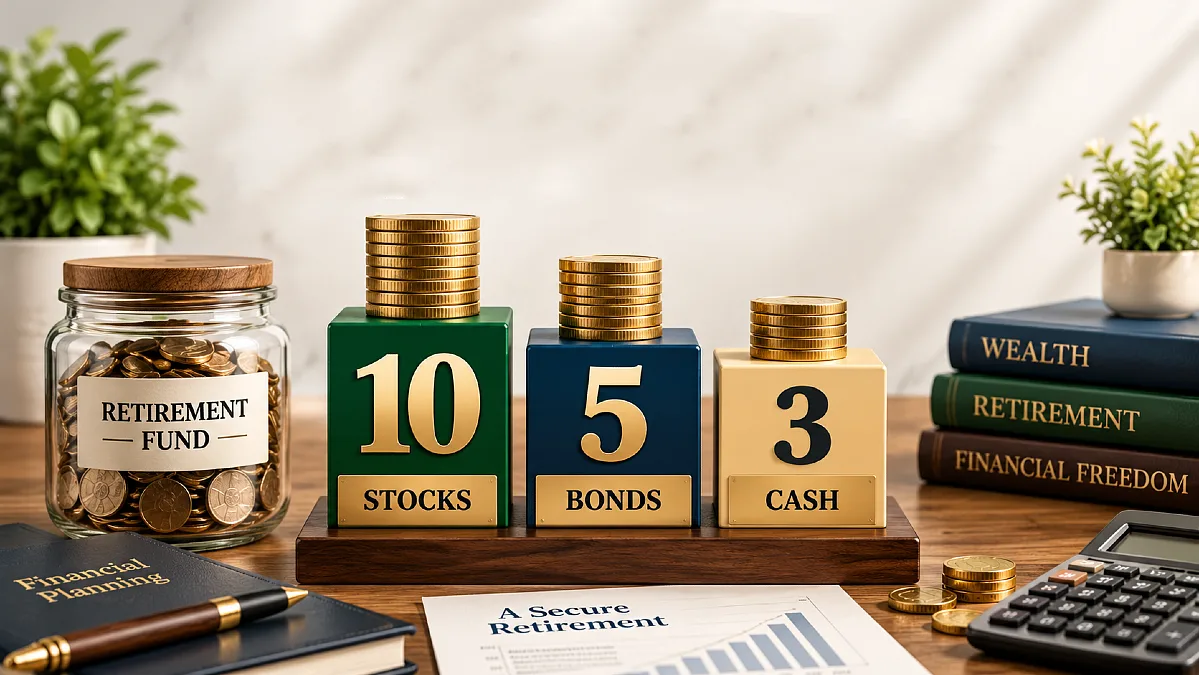
Retirement planning gets dangerous when a familiar investment average starts looking like dependable income. The 10-5-3 rule says stocks can return about 10% a year, bonds 5%, and cash 3%, but none of those figures is a promise.
A retiree who counts on those percentages to pay bills could be forced to sell investments after a market decline.
The gap between historical averages and future returns is bigger than many people expect.
A century of market history, updated 2026 forecasts, and a realistic $600,000 portfolio example reveal what retirees can reasonably plan for and why investment returns alone cannot determine sustainable spending.
What Is the 10-5-3 Rule in Retirement Planning?
The 10-5-3 rule is a simple investing guideline that assigns different long-term annual returns to three major asset classes. It assumes stocks earn around 10%, bonds earn 5%, and cash or cash equivalents earn 3%.
These percentages are broad historical reference points, not guaranteed investment rates. Their main purpose is to explain why different investments serve different roles inside a retirement portfolio.
Stocks represent growth. When investors own stocks, they own shares of businesses. Stock prices can rise as companies grow, and some stocks also pay dividends.
Over long periods, stocks have historically produced stronger returns than bonds or cash. However, their values can fall sharply, sometimes when retirees need money most.
Bonds represent income and relative stability. Bonds are loans made to governments, corporations, or other issuers. Investors generally receive interest payments and repayment of principal at maturity, assuming the issuer meets its obligations.
High-quality bonds often fluctuate less than stocks, although they can still lose market value. Interest rate changes, inflation, and credit risk all affect bond returns.
Cash represents liquidity and short-term protection. This category includes savings accounts, money market instruments, Treasury bills, and certificates of deposit.
Cash helps retirees cover immediate expenses without selling stocks during difficult markets. Its weakness is that inflation can reduce purchasing power over time.
The important distinction is that the 10-5-3 rule describes return assumptions, not how much money retirees should withdraw.
What 100 Years of Market History Actually Tells Us
The historical foundation of the 10-5-3 rule is stronger than its usefulness as a forecast might suggest.
In September 2026, the CFA Institute published Roger G. Ibbotson’s research examining U.S. market performance from 1926 through 2025.
According to that research, one dollar invested in U.S. large-company stocks at the beginning of the period grew to approximately $14,751 by the end. The same dollar invested in long-term Treasury bonds grew to about $117, while a dollar invested in short-term Treasury bills grew to approximately $25.
Those figures translate into approximate compound annual growth rates of 10.1% for large-company stocks, 4.9% for long-term Treasury bonds, and 3.3% for Treasury bills.
That is remarkably close to the familiar 10-5-3 formula. However, those returns cover 100 years of extremely different economic conditions.
The figures also assume investments remain in place, with returns reinvested, and do not represent an investor regularly withdrawing money.
One particularly revealing finding concerns inflation. Over the same century, the overall price level increased approximately eighteenfold, meaning cash-like investments produced much less real wealth growth than their nominal returns suggest.
A retiree should therefore treat 10-5-3 as a lesson about long-term investment behavior, not as an estimate of what the next year will deliver.
Why the 10-5-3 Rule Looks Different in 2026
The biggest problem with relying on historical returns is that investors cannot purchase yesterday’s market conditions.
Stock valuations, interest rates, earnings expectations, and inflation all influence what investments may earn in the future. Those conditions change, sometimes substantially.
Schwab Asset Management’s 2026 capital market expectations provide a useful comparison. Its estimates cover the 2026–2035 period and are based on information available through October 31, 2025.
These projections are annualized nominal returns, meaning they include inflation but do not account for individual investment fees or taxes.
| Investment Type | Traditional 10-5-3 Rule | Schwab 2026 Forecast | Primary Role |
|---|---|---|---|
| U.S. large-cap stocks | 10% | 5.9% | Long-term growth |
| U.S. aggregate bonds | 5% | 4.8% | Income and diversification |
| Cash equivalents | 3% | 3.3% | Liquidity and near-term spending |
The difference in stock expectations is especially important. A portfolio built around 10% stock growth may produce very different financial projections when that assumption falls to 5.9%.
Vanguard’s October 21, 2026 market outlook provides another perspective. Its updated 10-year annualized expectations range from 4.8% to 6.8% for U.S. equities and 5.1% to 6.1% for U.S. aggregate bonds.
Both firms’ forecasts suggest that retirees should be careful about assuming stocks will automatically repeat their century-long average over the coming decade.
These are model-based projections, not promises. Actual returns could be considerably higher or lower, and the forecasts do not predict what will happen in any single year.
The more useful lesson is that return assumptions should be reviewed periodically rather than treated as permanent numbers.
What the Rule Means for Someone Retiring With $600,000
Consider a hypothetical retiree with $600,000 invested across stocks, bonds, and cash.
Suppose the portfolio contains 50% stocks, 40% bonds, and 10% cash. That creates a balanced mix designed to provide growth while retaining a meaningful allocation to less volatile investments.
Under the traditional 10-5-3 rule, the portfolio’s weighted average return would be 7.3% annually. Under Schwab’s 2026 projections, the corresponding figure would be approximately 5.2%.
The difference becomes clearer when expressed in dollars.
| Portfolio Holding | Amount Invested | Annualized Amount at 10-5-3 Rates | Annualized Amount at Schwab Forecast Rates |
|---|---|---|---|
| Stocks | $300,000 | $30,000 | $17,700 |
| Bonds | $240,000 | $12,000 | $11,520 |
| Cash | $60,000 | $1,800 | $1,980 |
| Total | $600,000 | $43,800 | $31,200 |
These are mathematical illustrations of annualized return assumptions, not forecasts of actual income in the next year. They assume the starting allocation remains unchanged for calculation purposes and exclude taxes, fees, and withdrawals.
The traditional rule produces an estimated annual portfolio return that is $12,600 higher than the amount implied by Schwab’s newer assumptions.
Over a long retirement, a difference of more than two percentage points in annual growth can substantially affect ending wealth. But the impact depends on when returns occur, how much money is withdrawn, and how markets perform.
The example also reveals something frequently misunderstood.
A portfolio with an expected return of $31,200 does not necessarily provide $31,200 in dependable annual spending money.
Some returns come from rising stock or bond prices rather than interest or dividends. Those gains may disappear during a market decline, even when the long-term forecast remains reasonable.
Why Investment Returns Are Not the Same as Retirement Income
People saving for retirement usually focus on growing account balances. Retirees face an additional problem because their investments may need to fund regular living expenses.
A portfolio can achieve a respectable average return over 20 years and still struggle to support withdrawals during that period.
This happens because investment returns and retirement withdrawals measure different things.
An investment return describes how much an asset gains or loses. A withdrawal rate describes how much money someone removes from their portfolio to support spending.
For example, withdrawing 5% of a $600,000 portfolio produces $30,000 during the first year. That equals $2,500 per month before taxes.
But a 5% withdrawal rate is not automatically sustainable simply because the portfolio is expected to earn 5% or more.
Market losses, inflation adjustments, taxes, and withdrawals made during downturns can all affect how long the money lasts.
Morningstar’s retirement income research released in December 2025 estimated a 3.9% starting withdrawal rate for certain balanced portfolios under a 30-year retirement scenario. Its model assumed inflation-adjusted spending and a 90% probability of having money remaining at the end of the period.
For a $600,000 portfolio, a 3.9% initial withdrawal would equal $23,400 annually, or $1,950 per month.
That figure is lower than the portfolio’s projected average annual return under Schwab’s assumptions. The difference reflects the need to account for uncertain returns and ongoing withdrawals over many years.
Morningstar’s research is not a guarantee or a universal spending recommendation. It provides a useful reminder that the return a portfolio might earn and the amount a retiree can prudently spend are not interchangeable.
Inflation Can Quietly Shrink the Value of Cash
Cash often feels especially attractive after retirement because its account balance generally does not fluctuate the way stock prices do.
Someone holding $100,000 in a savings account can see exactly how much money is available. The problem is that the same dollar amount may buy less as prices rise.
Schwab’s 2026 capital market expectations include a long-term U.S. inflation assumption of 2.4%.
If a retiree’s expenses rise at that rate every year, a household spending $4,000 per month today would need considerably more money to maintain the same lifestyle later.
The following example assumes expenses rise by exactly 2.4% annually. Actual household inflation may differ, particularly for healthcare, insurance, housing, and other retirement expenses.
| Years From Now | Annual Spending Needed | Monthly Spending Needed |
|---|---|---|
| Today | $48,000 | $4,000 |
| 5 years | $54,043 | $4,504 |
| 10 years | $60,847 | $5,071 |
| 20 years | $77,133 | $6,428 |
After 20 years, the same lifestyle would cost approximately $29,100 more per year under these assumptions.
That increase does not necessarily mean the household is buying more goods or enjoying a more expensive lifestyle. It simply reflects the gradual rise in prices.
Now consider a cash investment earning 3.3% annually while inflation averages 2.4%.
After accounting for inflation, the annual increase in purchasing power would be approximately 0.9% before taxes.
This does not make cash a poor investment. It means cash is better suited to preserving short-term flexibility than providing all the growth needed across a 25- or 30-year retirement.
Retirees who keep nearly all their savings in cash may avoid daily stock market declines but still face the quieter risk of rising living expenses.
Why Cash Yields Today Do Not Guarantee the Same Income Tomorrow
There is another complication with the 3% cash assumption.
Cash yields are closely connected to prevailing interest rates. As interest rates change, savings accounts, money market instruments, and newly issued Treasury bills can offer different returns.
For example, U.S. Treasury data for October 28, 2026 showed a coupon-equivalent yield of approximately 4.11% on 13-week Treasury bills.
That was above the 3% cash return in the traditional rule. It was also above Schwab’s long-term 3.3% annualized cash forecast.
The figures are not contradictory because they measure different things.
The Treasury figure describes a market yield available at a particular time. Schwab’s forecast estimates what cash investments might earn on average over a much longer period.
A retiree buying a short-term Treasury bill can know the amount payable at maturity, assuming the U.S. government meets its obligations. However, there is no guarantee that an equally attractive rate will be available when the bill matures and the proceeds are reinvested.
This is called reinvestment risk, and it matters when someone expects short-term savings to generate dependable income year after year.
Bank deposits offer another important distinction. FDIC insurance generally protects eligible deposits up to $250,000 per depositor, per insured bank, per ownership category.
That protection relates to qualifying bank deposits, not the future purchasing power of money or the interest rate a bank will continue offering.
The Retirement Risk That Average Returns Cannot Explain
The timing of market gains and losses can matter almost as much as their overall average.
Financial planners call this sequence-of-returns risk. It becomes especially important when someone is withdrawing money from investments rather than adding new savings.
Imagine a hypothetical retiree beginning with $500,000 and withdrawing $20,000 at the start of each year.
Suppose the investment portfolio experiences a 20% decline in one year and a 25% gain in the other. Without withdrawals, those two returns would leave the original portfolio exactly where it started, regardless of their order.
With withdrawals, the outcome changes.
| Return Sequence | End of Year 1 | End of Year 2 | Final Balance |
|---|---|---|---|
| Down 20%, then up 25% | $384,000 | $455,000 | $455,000 |
| Up 25%, then down 20% | $600,000 | $464,000 | $464,000 |
Both scenarios begin with $500,000 and involve the same $40,000 in withdrawals. Both experience exactly the same two annual market returns, just in a different order.
Yet the retiree experiencing the loss first finishes with $9,000 less.
The reason is that withdrawals during a downturn remove money that would otherwise participate in the recovery. The portfolio has fewer dollars remaining to benefit when markets improve.
Over decades, the effect can become more serious, particularly when poor returns occur during the first several years of retirement.
This helps explain why a portfolio’s long-term expected return is not enough to determine how much a retiree should spend.
How Stocks, Bonds, and Cash Can Work Together in Retirement
The more useful application of the 10-5-3 rule is understanding the different jobs that investments perform.
A retirement portfolio does not need every dollar to grow at the same rate. Some money may be needed next month, while other savings may remain invested for another 20 years.
Cash helps cover immediate expenses. Retirees may use savings accounts, short-term Treasury bills, or other suitable liquid holdings for money they expect to spend soon.
Keeping funds readily available can reduce the need to sell stocks during an unexpected decline. The appropriate reserve depends on spending needs, other reliable income, and personal circumstances.
Bonds can help support medium-term spending. High-quality bonds can provide interest payments and may reduce portfolio volatility compared with an all-stock strategy.
However, bond funds do not promise a fixed account value. Bond prices can decline when interest rates rise, while individual bonds held to maturity have their own credit and liquidity considerations.
Stocks can support expenses many years into the future. A retiree who may live another 25 or 30 years still needs some exposure to investments capable of growing faster than inflation.
That does not mean every retiree needs a large stock allocation. The appropriate mix depends on financial resources, spending flexibility, risk tolerance, and how much income comes from Social Security or pensions.
The SEC’s investor education guidance emphasizes that asset allocation should reflect both investment time horizon and the ability to tolerate losses.
For retirees, that translates into a practical principle: money needed soon should not necessarily take the same risks as money intended for much later.
A $600,000 Portfolio May Need Less Income Than Its Owner Thinks
A retiree does not always need investment earnings to cover the entire household budget.
Consider another hypothetical example using the same $600,000 portfolio. Assume a retired couple spends $4,000 per month and receives a combined $2,600 monthly from Social Security.
Their annual expenses total $48,000, while Social Security provides $31,200.
That leaves an annual gap of $16,800, or $1,400 per month, to be covered by investments or other income.
The initial withdrawal need is therefore 2.8% of the $600,000 portfolio, before accounting for any additional taxes or irregular expenses.
This changes the retirement calculation significantly.
Rather than asking whether the portfolio can earn enough to produce $48,000 annually, the couple needs to determine whether it can reliably support their smaller portfolio withdrawal requirement over time.
For households with pensions, rental income, or other dependable income sources, the gap may be smaller still.
Of course, actual retirement spending may rise, and not every income source will keep pace with inflation. Major medical expenses, home repairs, family support, and changes in household circumstances can also affect the amount needed.
Still, this example shows why retirement planning should begin with expenses and reliable income rather than an assumed stock market return.
Four Mistakes Retirees Make When Applying the 10-5-3 Rule
.retire-mistakes { –navy: #142b43; –blue: #216c92; –red: #bb483d; –green: #19765f; –cream: #f5f7f8; font-family: Arial, Helvetica, sans-serif; max-width: 900px; margin: 25px auto; color: #243547; line-height: 1.5; } .retire-mistakes * { box-sizing: border-box; } .retire-mistakes .infographic { background: #f5f7f8; border: 1px solid #e1e7eb; border-radius: 16px; padding: 28px; } .retire-mistakes .header { background: #142b43; color: white; border-radius: 12px; padding: 32px 24px; text-align: center; } .retire-mistakes .eyebrow { color: #a8d8e8; font-size: 12px; font-weight: 800; text-transform: uppercase; letter-spacing: 2px; margin-bottom: 12px; } .retire-mistakes h2 { color: #fff; font-size: clamp(23px, 4vw, 34px); line-height: 1.18; margin: 0 0 14px; } .retire-mistakes .header p { color: #d4e3ef; font-size: 15px; max-width: 610px; margin: 0 auto; } .retire-mistakes .rule-bar { display: flex; justify-content: center; flex-wrap: wrap; gap: 9px; margin-top: 23px; } .retire-mistakes .rule-bar span { background: rgba(255,255,255,.11); border: 1px solid rgba(255,255,255,.2); border-radius: 7px; padding: 9px 14px; font-size: 13px; font-weight: 700; color: #fff; } .retire-mistakes .rule-bar strong { color: #9ee5d1; font-size: 17px; } .retire-mistakes .cards { display: grid; grid-template-columns: repeat(2, minmax(0,1fr)); gap: 16px; margin-top: 20px; } .retire-mistakes .mistake { background: #fff; border: 1px solid #e1e7eb; border-radius: 12px; padding: 22px; min-width: 0; box-shadow: 0 3px 12px rgba(20,43,67,.04); } .retire-mistakes .card-top { display: flex; align-items: center; gap: 10px; margin-bottom: 17px; } .retire-mistakes .number { width: 42px; height: 42px; flex-shrink: 0; display: flex; align-items: center; justify-content: center; border-radius: 10px; background: #fcebe7; color: #ad3e35; font-size: 19px; font-weight: 800; } .retire-mistakes .tag { font-size: 11px; font-weight: 800; text-transform: uppercase; letter-spacing: 1.2px; color: #b64e40; } .retire-mistakes h3 { font-size: 19px; line-height: 1.3; color: #142b43; margin: 0 0 12px; } .retire-mistakes .explain { font-size: 14px; line-height: 1.7; color: #536374; margin: 0 0 16px; } .retire-mistakes .visual { background: #edf3f7; border: 1px solid #e1eaf0; border-radius: 9px; padding: 17px 12px; text-align: center; min-height: 105px; display: flex; flex-direction: column; justify-content: center; margin-bottom: 17px; } .retire-mistakes .visual .big { font-size: 29px; line-height: 1.2; font-weight: 800; color: #216c92; } .retire-mistakes .visual .small { font-size: 12px; color: #627284; margin-top: 6px; } .retire-mistakes .comparison { display: flex; justify-content: center; align-items: center; gap: 12px; } .retire-mistakes .comparison .not-equal { font-size: 26px; color: #bb483d; font-weight: bold; } .retire-mistakes .comparison .figure { font-size: 23px; font-weight: 800; color: #216c92; } .retire-mistakes .bond-visual { display: flex; justify-content: center; align-items: center; gap: 20px; } .retire-mistakes .bond-visual .figure { font-size: 25px; font-weight: 800; } .retire-mistakes .bond-visual .up { color: #bb483d; } .retire-mistakes .bond-visual .down { color: #216c92; } .retire-mistakes .bond-visual .vlabel { font-size: 12px; color: #536374; } .retire-mistakes .visual .math-line { display: flex; justify-content: center; flex-wrap: wrap; gap: 6px; align-items: center; } .retire-mistakes .visual .math-line span { font-size: 12px; font-weight: 700; padding: 7px 9px; border-radius: 5px; background: white; border: 1px solid #dbe5ec; } .retire-mistakes .visual .math-line b { color: #bb483d; } .retire-mistakes .fix { background: #e9f5f0; border-left: 4px solid #19765f; padding: 13px; border-radius: 0 7px 7px 0; } .retire-mistakes .fix strong { display: block; color: #13634e; font-size: 12px; text-transform: uppercase; letter-spacing: .6px; margin-bottom: 5px; } .retire-mistakes .fix p { font-size: 13px; color: #294b43; margin: 0; line-height: 1.6; } .retire-mistakes .takeaway { background: #142b43; border-radius: 12px; padding: 23px; margin-top: 19px; text-align: center; color: white; } .retire-mistakes .takeaway h3 { color: #9ee5d1; font-size: 20px; margin: 0 0 9px; } .retire-mistakes .takeaway p { color: #e1edf4; font-size: 14px; line-height: 1.7; margin: 0 auto; max-width: 650px; } .retire-mistakes .footer { text-align: center; font-size: 12px; color: #708092; margin-top: 15px; } @media(max-width: 650px) { .retire-mistakes .infographic { padding: 12px; } .retire-mistakes .header { padding: 26px 16px; } .retire-mistakes .cards { grid-template-columns: 1fr; gap: 13px; } .retire-mistakes .mistake { padding: 19px; } .retire-mistakes .rule-bar span { padding: 8px 10px; font-size: 12px; } }4 Costly Mistakes With the 10-5-3 Rule
Historical investment averages can help with planning. But treating them like guaranteed income can put retirement savings at risk.
Expecting 10% From Stocks Every Year
A long-term average is not a guaranteed annual return. Stocks can lose significant value even during decades with positive overall growth.
Test your retirement plan using weaker market returns and possible stock losses.
Believing Bonds Cannot Lose Money
Bonds are often less volatile than stocks, but their market prices can fall when interest rates rise. Longer-term bonds are generally more sensitive to rate changes.
Review bond maturity, credit quality, interest rate risk, and fund structure.
Confusing Total Return With Cash Income
Investment returns may include price gains, dividends, and interest. A fund rising 8% in value has not necessarily paid investors 8% in spendable cash.
Create a withdrawal plan that explains how investments will fund monthly expenses.
Ignoring Inflation, Taxes, and Fees
A 5% investment return does not mean your purchasing power grows by 5%. Inflation, investment costs, and applicable taxes reduce the amount you effectively keep.
Evaluate returns after inflation, fees, and taxes when estimating retirement spending.
The Retirement Planning Lesson
Use the 10-5-3 rule to understand the different roles of stocks, bonds, and cash. Do not treat historical returns as guaranteed yearly income. Build a plan that can handle market declines, rising living costs, and changing withdrawal needs.
How to Build a More Realistic Retirement Return Plan
A practical retirement strategy can begin with a few straightforward calculations rather than complicated financial projections.
The first step is identifying how much spending must come from investments. After that, retirees can consider when the money is needed and what investment risks are reasonable.
| Planning Priority | What to Check | Practical Next Step |
|---|---|---|
| Immediate expenses | Spending not covered by reliable income | Maintain an appropriate liquid reserve |
| Next several years | Planned withdrawals and large purchases | Review short-term bonds, Treasury bills, and cash needs |
| Long-term expenses | Inflation and retirement length | Evaluate diversified stock exposure |
| Annual review | Returns, fees, allocation, and spending | Update projections and rebalance when appropriate |
These are planning categories, not a required investment allocation. Someone with substantial guaranteed income may need a different mix from someone who relies almost entirely on retirement savings.
A useful planning exercise is to create at least three scenarios.
The optimistic scenario might assume stronger investment growth and relatively stable expenses. A middle scenario would use reasonable forward-looking expectations rather than automatically assuming historical stock returns will repeat.
The cautious scenario should consider weaker investment performance, early market losses, and higher-than-expected expenses.
Retirees should also examine how much spending they could adjust temporarily during a difficult period. Households with flexible travel, entertainment, or discretionary budgets may have more room to respond than households whose expenses are largely fixed.
Finally, projections should be updated as circumstances change. Investment expectations, health needs, retirement income, and household spending are unlikely to remain identical for decades.